Why Is Money So Hard With ADHD?
Because the skills money management depends on are the ones ADHD affects: planning ahead, holding information in mind, resisting immediate reward and doing tedious admin on time. Research has linked ADHD with greater preference for immediate rewards and difficulties with some aspects of financial decision-making, including impulsive buying and saving, although these relationships are influenced by other factors such as personality and mood. For many people, changing the system is more sustainable than relying on willpower alone.
ADHD and money is one of the least-discussed parts of adult ADHD and one of the most expensive. ADHD and financial management run into each other for structural reasons rather than because of carelessness, and ADHD and managing money day to day is a different problem from earning enough. This guide covers what the research shows, what the ADHD tax actually costs, and the systems that work. It is general information rather than financial advice, and it is not personal financial guidance. For the wider adult picture, see the guide to ADHD in adults.
What the Research Shows
A Dutch and German study compared 45 adults with ADHD against 51 adults without, matched on age, gender, education and employment, with students excluded because of financial dependence. The differences were substantial.
- Median income was markedly lower in the ADHD group
- Around half of the ADHD group reported non-mortgage debt, against about a third of the comparison group
- Slightly over half of the ADHD group had savings accounts, compared with more than six in seven of the comparison group
- The comparison group was around four times more likely to own a home
- The ADHD group showed higher propensity to buy on impulse, and greater temporal discounting, meaning a stronger preference for immediate reward over longer-term financial security
- Scores were lower on financial competence measures, particularly financial judgement and management, with avoidant and spontaneous decision styles more common
Two things from that study matter more than the numbers. Only three of nine cognitive measures differed between groups, and the authors concluded that differences in cognitive functioning cannot fully explain the financial disparities. This is not simply a matter of ability. And the sample was small, participants were off medication during testing, and the findings describe group patterns rather than any individual’s trajectory.
A larger 2020 community study is important context. It also found higher impulsive-buying scores and more avoidant and spontaneous decision styles in people with ADHD symptoms, but after controlling for personality, depression and demographic factors, ADHD symptoms were no longer significant predictors. A separate meta-analysis of temporal discounting found small-to-medium effects rather than large ones. Taken together, the association is real and the causal picture is more complicated than ADHD alone.
What the Research Does and Does Not Establish
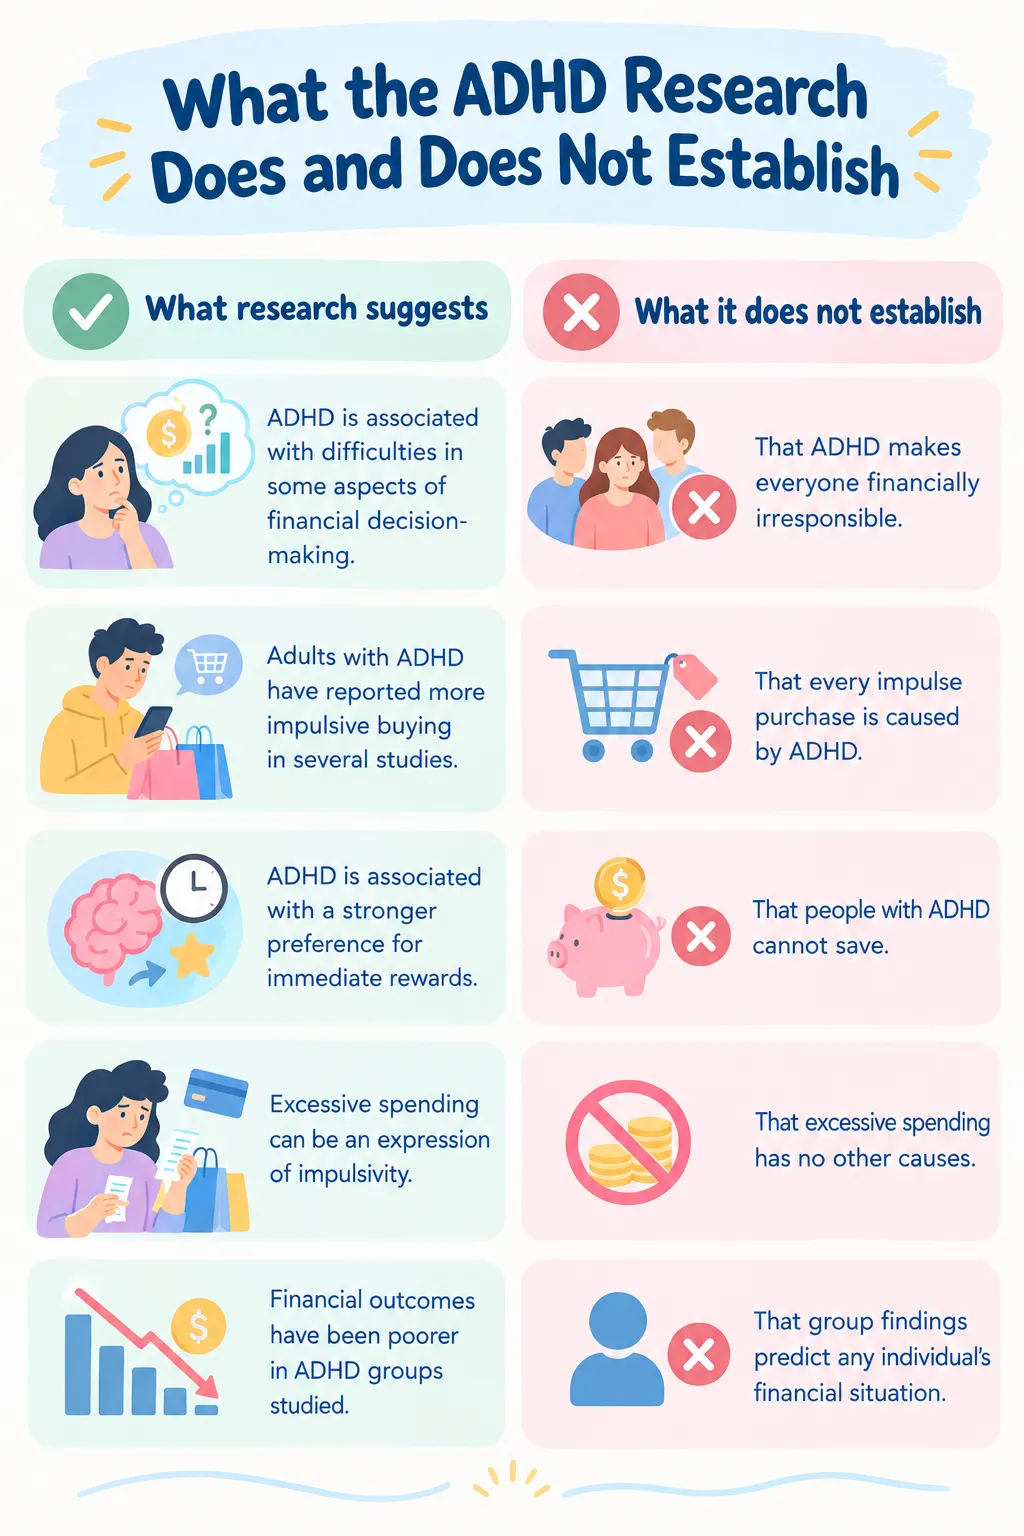
| What research suggests | What it does not establish |
| ADHD is associated with difficulties in some aspects of financial decision-making | That ADHD makes everyone financially irresponsible |
| Adults with ADHD have reported more impulsive buying in several studies | That every impulse purchase is caused by ADHD |
| ADHD is associated with a stronger preference for immediate rewards | That people with ADHD cannot save |
| Excessive spending can be an expression of impulsivity | That excessive spending has no other causes |
| Financial outcomes have been poorer in ADHD groups studied | That group findings predict any individual’s financial situation |
Australia’s clinical guideline separately documents reduced income and lower occupational achievement among adults with ADHD, which compounds everything on this page (Australian ADHD Professionals Association, 2022).
The ADHD Tax
The ADHD tax is an informal term, not a clinical one. It describes the money ADHD costs you that has nothing to do with what you actually bought, and it is genuinely useful because it makes an invisible cost visible.
| Where it goes | What it looks like |
| Late fees and interest | Bills and card payments missed by days, not by inability to pay |
| Subscriptions | Free trials that converted, services no longer used, memberships that renewed unnoticed |
| Fines and penalties | Parking tickets left until they escalate, overdue charges, toll notices |
| Duplicate purchases | Replacing things you own but cannot find, then finding them |
| Wasted food | Groceries bought with intent and thrown out unopened |
| Prepaid and unused | Classes, courses and packages bought in a burst of enthusiasm and never used |
| Expedited everything | Rush shipping, last-minute flights, express fees for things that could have been done earlier |
| Missed appointments | Cancellation fees for appointments forgotten or misremembered |
The emotional half of the ADHD tax is the part that does the lasting damage. Each of these is small, each feels like a personal failure, and the accumulated evidence builds into a belief about being bad with money that then makes avoidance worse. ADHD and money problems tend to compound this way rather than arriving all at once, and ADHD and financial problems are frequently the visible end of a long run of small ones. Naming the pattern as a predictable consequence of a known mechanism is not an excuse; it is the thing that makes it addressable.
Why ADHD Makes Money Harder
| Mechanism | What it does to money |
| Delay discounting | Future money feels less real than present money, so saving competes badly against spending now |
| Impulsivity | The gap between wanting and buying is very short, and online shopping has removed most of what used to slow it |
| Working memory | Knowing what you have already spent this week requires holding it in mind, which is the specific difficulty |
| Time estimation | Bills arrive sooner than expected and the money that was meant for them is gone |
| Task initiation | Admin that takes ten minutes goes undone for six weeks, and costs money in the meantime |
| Avoidance and shame | Unopened mail and unchecked balances, because looking confirms something you already feel bad about |
| Stimulation seeking | Buying provides novelty and a mood change, which is a different motivation from wanting the object |
Money blindness
Money blindness is another informal term, used by some people with ADHD to describe difficulty maintaining a current mental picture of their finances: knowing roughly, in the way you know roughly what time it is when you have not looked at a clock. It is the financial equivalent of time blindness and it has the same fix. You do not develop the sense by trying harder; you put the number somewhere you will see it without having to check.
Systems That Work
One principle carries most of the value here: remove the decision from the moment it would have to be made. Every system below is a version of that.
Automate first
- Direct debit every fixed bill you can, timed just after payday rather than mid-cycle
- Automatic transfer to savings on payday, before the money is visible as spendable
- Separate accounts by purpose: bills, spending, savings. Money that is not in the spending account is not a decision you have to make
- Bank alerts for low balance and for every transaction above a threshold you choose
- Calendar reminders for anything that cannot be automated, including annual renewals
Make it visible
- One app, checked at a set time, rather than several checked when you remember
- A recurring weekly money appointment of ten minutes, in the calendar, ideally with someone else present
- Balance visible on your phone home screen or as a widget, so seeing it is not a decision
Add friction to spending
- Remove saved card details from the browsers and apps you use most
- A waiting period on anything over an amount you set. A pause between the urge to buy and the purchase gives the impulse time to pass
- Unsubscribe from retail email and turn off shopping notifications, which removes the prompt rather than resisting it
- Use a separate low-balance card for discretionary spending, so the limit is structural
Budgeting With ADHD
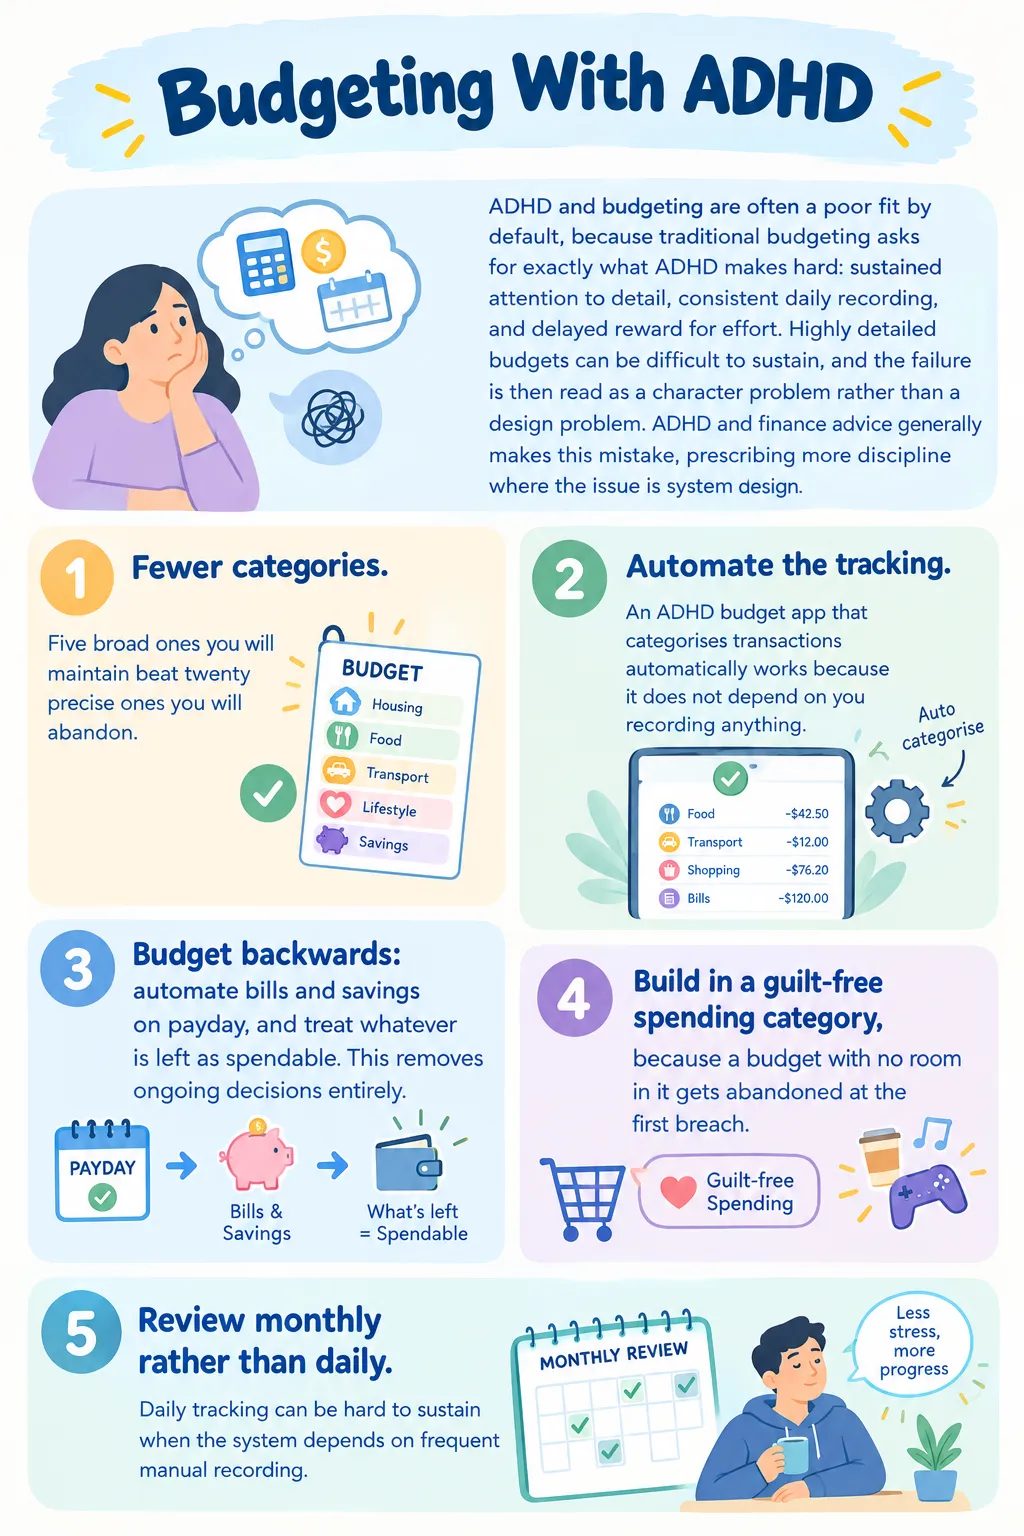
ADHD and budgeting are often a poor fit by default, because traditional budgeting asks for exactly what ADHD makes hard: sustained attention to detail, consistent daily recording, and delayed reward for effort. Highly detailed budgets can be difficult to sustain, and the failure is then read as a character problem rather than a design problem. ADHD and finance advice generally makes this mistake, prescribing more discipline where the issue is system design.
- Fewer categories. Five broad ones you will maintain beat twenty precise ones you will abandon
- Automate the tracking. An ADHD budget app that categorises transactions automatically works because it does not depend on you recording anything
- Budget backwards: Automate bills and savings on payday, and treat whatever is left as spendable. This removes ongoing decisions entirely
- Build in a guilt-free spending category, because a budget with no room in it gets abandoned at the first breach
- Review monthly rather than daily: Daily tracking can be hard to sustain when the system depends on frequent manual recording
An ADHD budgeting template is worth using if it is simple enough that you will open it twice. If you have spent more time designing the template than using it, that is procrastination wearing a productivity costume, and the answer is a simpler system rather than a better one.
Impulse and Compulsive Spending
ADHD and spending money is where the research is most consistent: impulse buying propensity has been found higher in several studies, though other factors including personality and mood contribute. Australia’s clinical guideline lists excessive spending among the ways impulsivity can present in adults.
ADHD and compulsive spending is worth distinguishing from ordinary impulse buying. Where spending is being used to change how you feel, where it is escalating, where it is being concealed, or where it continues despite serious consequences, that is a different problem. When spending is causing significant distress or harm, discussing it with a GP or psychologist can be more appropriate than relying on budgeting tools alone. Compulsive buying also occurs alongside other conditions.
Debt, Bills and Saving
ADHD and paying bills
For some people with ADHD, missed bills reflect timing, attention or administrative overload even when the money is available. Those are the ones systems fix. Direct debit, aligning due dates to just after payday where providers allow it, and a single place where bills go all remove the failure point. Where affordability genuinely is the issue, most Australian utilities and lenders have hardship programs, and asking early produces better outcomes than asking late.
ADHD and debt
Debt accumulates differently with ADHD: less often through one large decision and more often through many small ones, plus interest and fees on amounts that were affordable at the time. Avoidance then compounds it, because the statement goes unopened.
ADHD and saving money
Saving asks you to prefer a distant benefit over an immediate one, which is precisely what temporal discounting makes harder. Automation is the answer: money moved on payday before it registers as available never has to compete. Making the goal concrete and visible, and shortening the horizon, both help more than resolving to save.
If Money Is Already a Problem
This is the part worth knowing regardless of ADHD. In Australia, financial counsellors provide free, confidential advice. They do not lend money or sell anything, and they work only in your interest. A financial counsellor is not the same as a financial adviser: counsellors help with debt and hardship, while advisers provide regulated personal financial advice under a different framework and usually charge for it.
- The National Debt Helpline is free and confidential on 1800 007 007, weekdays 9:30am to 4:30pm, with live chat available weekdays 9:00am to 8:00pm
- They can help with utilities, mortgages, credit cards, payday loans, tax debts and hardship arrangements
- Contacting them early gives more options than contacting them late, and avoidance is the thing that closes options
- If shame is the barrier, it may help to know that financial counsellors do this work all day and are not there to judge the decisions that got you there
Details were checked in September 2026; confirm current hours before relying on them.
Related Guides
- ADHD at work: rights, adjustments and what helps
- Impulsivity and hyperactivity in ADHD
- ADHD paralysis: why starting is the hard part
- Is ADHD a disability, a disorder or a difference?
- ADHD and relationships
References
- Financial decision-making in adults with ADHD. 2019. Study of 45 adults with ADHD and 51 matched controls covering income, debt, savings, impulse buying and temporal discounting. PMID 31343233
- ADHD and the choice of small immediate over larger delayed rewards: a comparative meta-analysis of performance on simple choice-delay and temporal discounting paradigms. 2018. Reports small-to-medium effects. PMID 29806533
- National Debt Helpline, an Australian financial counselling service. Free and confidential. ndh.org.au
- Financial decision-making in a community sample of adults with and without current symptoms of ADHD. PLOS One, 2020.
- Australian ADHD Professionals Association. Australian Evidence-Based Clinical Practice Guideline for Attention Deficit Hyperactivity Disorder (ADHD). Released October 2022. Impulsivity in adults and functional impact on income and occupational achievement. adhdguideline.aadpa.com.au
- National Debt Helpline. Free and confidential financial counselling. ndh.org.au
- Attention Deficit Disorder Association. The ADHD tax: hidden costs and strategies. add.org
Last reviewed: September 2026. Next scheduled review: September 2027. This article is general information and is not a substitute for individual medical advice, assessment or diagnosis.